Geopolitical Disruption and Longer Voyages Squeeze Vessel Availability
By Amy McLellan
The breakbulk sector is facing a capacity squeeze, but the problem is not necessarily a lack of vessels.
According to speakers on the Fleet Decisions in an Era of Strategic Demand panel session at Breakbulk Americas 2026, changing trade routes, geopolitical disruption and sustained demand for project cargo are keeping vessels employed for longer, making available capacity increasingly difficult to secure.
“The maritime breakbulk sector is facing a moment of real consequence right now,” said Thomas Damsgaard, head of Americas at BIMCO and session moderator. “The fleet is aging, vessel availability is tightening, and needless to say, geopolitical pressures are reshaping global capacity into ways that affect nearly every part of the project logistics supply chain.
“Limited newbuild activity makes it more difficult to replace aging vessels, while rising demand for project cargo, energy infrastructure, construction materials and government-supported development in placing additional pressure on an already constrained marketplace for project and heavy-lift cargo.”
The effects are being felt throughout the project logistics chain, Damsgaard said, with constraints on vessels, ports, inland transport and specialist handling potentially feeding through into construction schedules and commissioning dates.
Phillip Brown, global chartering manager at Bechtel Global Logistics, said the changing pattern of trade has already altered the availability and timing of transport. The impact of the Iran-US conflict, restrictions and uncertainty around the Panama Canal, and potential Section 301 measures were contributing to significant changes in trade lanes.
At the same time, cargo volumes from the Far East were increasing demand for tonnage, while longer waiting times at Chinese and Korean ports were affecting voyage planning and transit times. The result, he said, was a perceived capacity shortage that was partly being created by vessels spending longer on each voyage.
“It’s not that there’s not enough vessels,” Brown told listeners. “It’s just that the vessels are taking longer per voyage based on routing.”
Rising to the Demand Challenge
 Demand is particularly strong in the power sector, driven by projects such as new semiconductor manufacturing facilities and data centers. Brown expects demand to remain high through 2027, putting further pressure on already constrained logistics networks.
This sustained demand is also creating challenges for U.S.-flag shipping. Will Terrill, executive vice president, commercial and growth at US Ocean, said proposed legislation covering cargo preference and shipbuilding needs to provide greater clarity on the long-term demand that would justify investment in additional US-flag capacity.
Meanwhile, flexibility may be as important as fleet size in responding to the market.
Melanie Drehkopf, CCO at dship Carriers, said the company had designed its D500 newbuilds around changing cargo requirements, with large deck space and a forward bridge among their features. But she stressed the importance of adapting to routes, ports and bunkering arrangements as market conditions change.
Lilian Wee, commercial manager at Roll Group Americas, also argued that the central issue was not whether there were enough vessels, but whether ships were adaptable enough to meet changing project requirements.
“Geopolitical situations in the Red Sea and Strait of Hormuz are happening and evolving really quickly,” she said, adding that carriers need to “think on our feet” and find ways to extract more value from existing fleets.
Long-term fleet investment presents another challenge. Drehkopf noted that a vessel built today could remain in service for 20 to 25 years, making it essential for owners to understand customers’ future requirements — from the size of wind turbines and generators to the equipment needed to handle them — before designing new ships.
The panelists also highlighted China’s dominance of MPV shipbuilding. Terrill said the country was responsible for 100% of recent and current construction of MPVs above 14,000 dwt, reflecting its competitive position.
Rather than competing directly on price, Wee said operators needed to differentiate through flexibility, value and more creative contractual and project solutions.
For cargo owners and project developers, the message was clear: securing transportation can no longer be treated as a late-stage logistics exercise. As Brown put it, project teams are increasingly having to “get more creative” to find solutions in this challenging and unpredictable world.
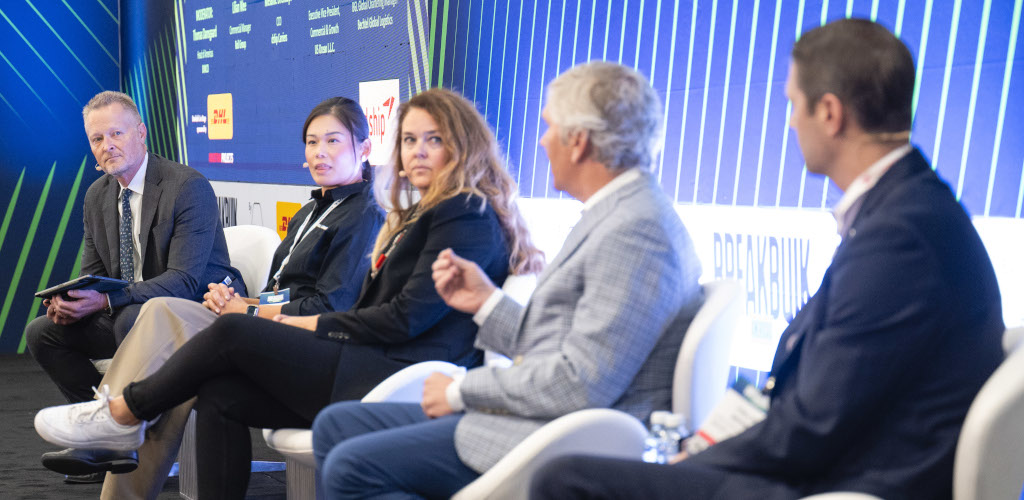
Top photo (L-R): Thomas Damsgaard, Lilian Wee, Melanie Drehkopf, Will Terrill, Phillip Brown. Credit: Marco Wang Photography
Second: Will Terrill and Phillip Brown. Credit: Marco Wang Photography